Read this article in 中文 Français Deutsch Italiano Português Español
Supply chain, costs weigh down Class 8 market outlook
11 November 2026
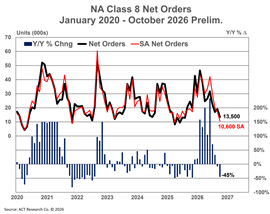
Class 8 preliminary orders in September totaled 18,700 units, down 9.5% year-over-year, according to ACT Research’s latest North American Commercial Vehicle OUTLOOK, as regulatory uncertainty and supply chain challenges continue to cloud fleet planning and equipment demand. The trend appears set to continue, with preliminary net orders totaling just 13,500 units in October*, down 45% year-over-year.
ACT Research said the consecutive decline – in spite of the continued strength in spot freight rates – reflects a combination of unresolved regulatory questions ahead of EPA 2027 implementation, ongoing cost pressures and midterm political uncertainty. The economy story is also mixed.
While underlying private domestic demand in the U.S. economy reached its strongest growth rate in over three years in Q2’26, ACT Research reported, persistent shocks from tariffs, elevated energy prices and rising interest rates are constraining purchasing power and raising business costs. AI-driven investment and a resilient manufacturing sector are offsetting continued weakness in housing, but higher borrowing costs and supply chain disruptions are tempering demand for capital goods.
“Fleets are eager to replace aging equipment and prepare for anticipated cost increases, but the ability to plan remains hampered by economic and regulatory uncertainty as well, at least into the medium-term, the evolving supply chain landscape,” said Ken Vieth, ACT’s president and senior analyst. “The recent decline in Class 8 orders in part reflects not only these headwinds, but materially higher backlogs now than at this time last year, and the impact of uncertainty around the final EPA’27 rule. Rather than a sudden drop in underlying demand, in the case of Class 8, fleets weigh their options in a shifting market.”
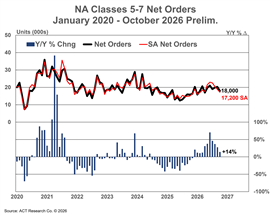
Medium-duty demand showed more resilience, with preliminary Classes 5-7 net orders rising 14% year-over-year to 18,000 units in October, continuing the segment’s recovery from last year’s soft volumes, the organization noted in its State of the Industry: Classes 5-8 Vehicles report.
“While spot rates remain supportive of equipment demand, the lack of clarity around EPA 2027 rules and associated costs has left OEMs and fleets unable to plan for next year,” said Carter Vieth, research analyst at ACT Research. “It’s not a lack of desire for new equipment holding fleets back, but rather the inability to make informed investment decisions in the face of regulatory and economic uncertainty.”
* Complete industry data for October, including final order results, will be published by ACT Research in mid-November.
POWER SOURCING GUIDE
The trusted reference and buyer’s guide for 83 years
The original “desktop search engine,” guiding nearly 10,000 users in more than 90 countries it is the primary reference for specifications and details on all the components that go into engine systems.
Visit Now
CONNECT WITH THE TEAM