Read this article in 中文 Français Deutsch Italiano Português Español
Monthly sales of BE truck in China break 50% barrier
05 November 2026
In 2024, battery-electric (BE) trucks in China accounted for 13.6% of the market. This increased to about 29% in 2025.
Now, sales of BE trucks in China have reached a new milestone. In September this year, sales accounted for 50.3% of the market, breaching the 50% barrier for the first time.
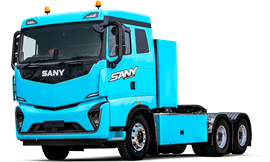 Sany SE equipped with the maximum 861 kWh battery packs (Photo: Sany)
This is the first time that BE trucks have outsold their diesel and LNG equivalents.
Major manufacturers of the medium- and heavy-duty vehicles include XCMG, Sany, FAW and Yutong. Aside from these established brands, new entries from companies such Sitrek (part of Sinotruk) and DeepWay are also proving popular.
Sales of BE trucks in China account for around 90% of all global sales. There are a series of reasons for such popularity.
To start, the national government in China has offered attractive scrappage/trade-in schemes for customers looking to make the switch from diesel to electric power.
There is also the lower total cost of ownership. It is reported that lower recharging costs in comparison to diesel fuel and reduced maintenance outlay can cut operating expenses by between 10 and 26%.
Then there is the exponential growth of battery swapping facilities. Located on major transport routes, these can exchange depleted batteries for fully-charged examples in about five minutes, reducing downtime and getting trucks back on the road.
Such is the volume shift towards BE trucks that there has been a sharp decline in demand for diesel fuel across China.
While demand cannot match that of China, European sales of BE trucks are continuing to increase. In late September, Bloomberg reported that sales of BE trucks in Norway, Switzerland and Denmark accounted more than 10% of those markets. In total, BE trucks accounted for 5.5% of all European truck sales in the first half of 2026.
In the United States, sales of BE trucks are said to be ‘at a standstill’, largely due to policy and cost headwinds. This, despite the TCO benefits in some applications when compared to diesel models.
POWER SOURCING GUIDE
The trusted reference and buyer’s guide for 83 years
The original “desktop search engine,” guiding nearly 10,000 users in more than 90 countries it is the primary reference for specifications and details on all the components that go into engine systems.
Visit Now
CONNECT WITH THE TEAM